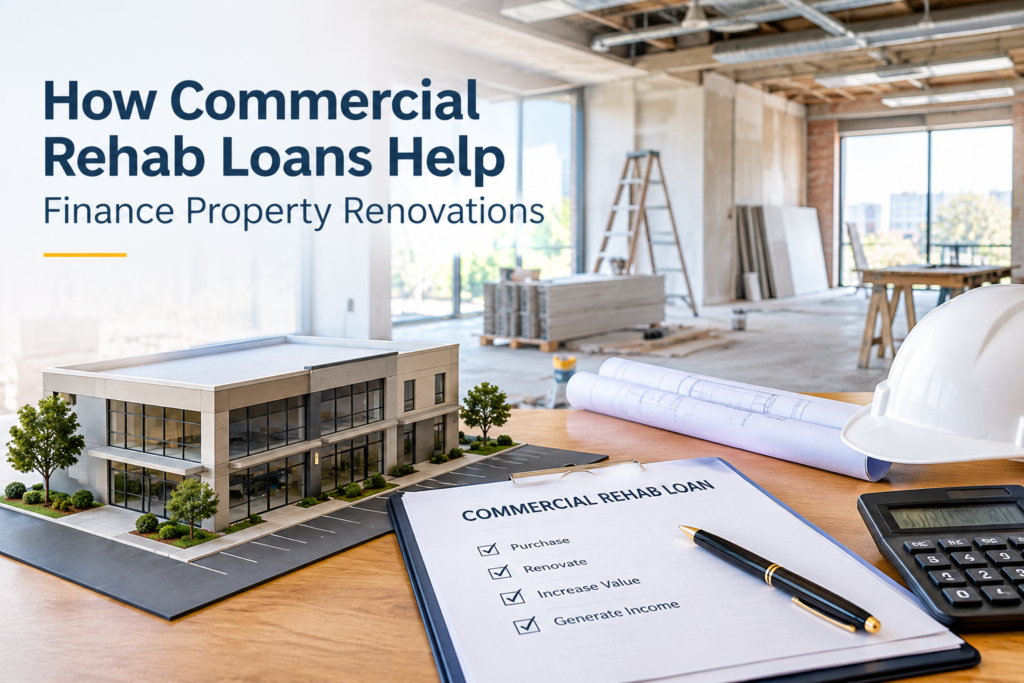
You’ve found a property with genuine potential the location works, the price is right, but the building itself needs serious work before it’s worth anything close to market rate. That gap between “as-is” and “possible” is where a lot of good deals fall apart, simply because the financing doesn’t exist to bridge it. A commercial rehab loan is built specifically for that gap.
Most commercial mortgages only finance the property as it sits today. If you’re buying a distressed office building or a retail space that needs a full remodel, a standard loan won’t cover the renovation costs you’d need a second loan, a second approval process, and a second closing. Rehab loans solve this by wrapping the purchase and the renovation into one deal, which is a big part of why they’ve become a go-to tool for commercial investors.
What Exactly Is a Commercial Rehab Loan?
At its core, it’s a short-term loan that funds both the acquisition of a commercial property and the cost of fixing it up. Lenders underwrite these loans a little differently than a typical mortgage instead of just looking at what the property is worth right now, they also look at what it’ll be worth once the work is done. That projected number is called the after-repair value, or ARV, and it’s often what determines how much you can actually borrow.
These loans show up across a wide range of commercial projects:
- Office buildings that need modernizing to stay competitive
- Retail spaces being remodeled to land new tenants
- Multifamily or mixed-use buildings getting unit-by-unit upgrades
- Warehouses or industrial space needing structural repairs
- Adaptive reuse projects think old factory turned into loft apartments
Because the lender is essentially betting on the property’s future value, borrowers can often access more capital than they would with conventional financing tied only to current appraised value.
How the Financing Actually Works
There’s usually a fairly consistent structure behind these loans:
The acquisition portion covers a chunk of the purchase price often somewhere in the 75-80% loan-to-value range. Separately, the renovation portion can cover a much larger share of construction costs, sometimes close to 100%. But that renovation money doesn’t just land in your account all at once. It gets released in draws, meaning you request funds as work gets completed and verified, stage by stage. It’s a system that protects the lender from funding work that never happens, and protects the borrower from a lender who wants everything documented before any renovation begins.
Terms tend to run short typically 12 to 24 months because the whole point is to get in, complete the renovation, and either sell or refinance. These aren’t designed to be long-term holds.
One thing that surprises a lot of first-time borrowers: approval often depends more on the deal itself the property’s potential, the renovation plan, the exit strategy than on years of tax returns and income documentation. That’s a real departure from how conventional bank underwriting works.
Why Investors Lean on Rehab Financing
Speed is probably the biggest draw. Traditional commercial mortgages can take months to close. Rehab loans, especially through private or hard money lenders, can sometimes close in a few weeks, which matters a lot when you’re competing for a property against other buyers.
There’s also the simplicity factor one loan, one lender, one closing, instead of stitching together separate financing for the purchase and the construction. And because the loan is structured around the property’s improved value rather than its current condition, it opens the door to properties that would otherwise be out of reach: distressed buildings, outdated retail centers, underperforming multifamily assets the kind of deals where the upside only exists after real money goes into the work.
Where Alternative Business Lending Comes In
Not everyone fits neatly into a bank’s box. Maybe the timeline is too tight, maybe the property is a little unconventional, or maybe the borrower’s financial documentation doesn’t check every box a traditional lender wants. This is where alternative business lending becomes relevant.
Alternative lenders private lenders, hard money shops, non-bank financial companies generally take a more flexible approach to underwriting. They tend to weigh the strength of the property and the renovation plan more heavily than a borrower’s credit score or business history. For investors who need to move fast or don’t fit conventional lending criteria, that flexibility can be the difference between closing the deal and losing it to someone else.
A few options that fall under this umbrella and often work alongside or in place of a commercial rehab loan:
- Hard money loans short-term, asset-based financing well suited to fix-and-flip or value-add deals
- Bridge loans short-term funding that covers the gap between purchase and eventual refinancing
- Business lines of credit helpful for renovation work that happens in phases rather than all at once
- SBA 504 and 7(a) loans government-backed programs for owner-occupied commercial properties, typically with longer terms and lower rates
Knowing both the ins and outs of commercial rehab loans and the broader world of alternative business lending gives investors more room to structure a deal that actually fits their property, their timeline, and their risk tolerance.
What Lenders Want to See
Requirements shift from lender to lender, but a few things come up consistently: the property’s as-is and after-repair value, a detailed renovation budget and timeline, the borrower’s track record with similar projects if they have one, a reasonably solid credit profile, and maybe most importantly a clear exit strategy. Lenders want to know how you plan to get out: sell, refinance, or hold. Walking into the application with these pieces already organized tends to speed things up considerably.
A Few Things Worth Considering First
These loans aren’t free of trade-offs. Interest rates run higher than what you’d see on a conventional commercial mortgage, which makes sense given the shorter term and higher risk profile. The short repayment window also means you need a realistic plan for what happens after renovations wrap up this isn’t financing meant to be held indefinitely. And since funds are typically released in draws tied to project milestones, having a dependable contractor and a realistic timeline matters just as much as the financing itself.
Bringing It Together
A commercial rehab loan gives investors a genuine path to turn an underperforming property into something worth real money, without needing to juggle separate financing for the purchase and the renovation. Pair that with a working knowledge of alternative business lending, and you’ve got access to capital that moves faster and bends more than what most traditional banks offer.
If you’re weighing a value-add commercial project, the financing structure deserves just as much attention as the renovation plan. A lender who understands both commercial rehab and alternative lending can help make sure the numbers, the timeline, and the terms actually line up.
FAQs
1. What’s the difference between a commercial rehab loan and a regular commercial mortgage?
A standard commercial mortgage finances the property as it currently exists. A commercial rehab loan covers both the purchase price and the renovation costs in a single loan, based partly on the property’s projected after-repair value.
2. How fast can a commercial rehab loan close?
It varies by lender, but private and hard money lenders often close within a few weeks, compared to the months a conventional bank loan can take.
3. Do I need strong credit to qualify?
Not necessarily. Many rehab lenders focus more on the property’s value, the renovation plan, and the exit strategy than on a borrower’s credit score, though credit still plays some role in the terms offered.
4. How does the draw schedule work?
Rather than receiving the full renovation budget upfront, funds are released in stages as work is completed and verified by the lender, which keeps the project on track and protects both parties.
5. What happens at the end of the loan term?
Since these are short-term loans, typically 12 to 24 months, borrowers usually need to sell the renovated property or refinance into longer-term financing once the work is complete.